The Next Great Homebuilder Won't Look Like a Homebuilder at All
By Peter Yoder. . 12 minute read.
“When producers say that the problem is that costs are high or that projects don’t pencil, they are a few steps ahead of the medieval priest."
A House Is Four Numbers
Every house you have ever seen is the sum of four costs.
Dirt: the land under it, plus the streets and pipes that serve it.
Structure: the physical building.
Money: the cost of financing the whole dance.
Margin: what the developer keeps for taking the risk.
The starter home died because policy quietly inflated the first number, law deformed the second, plumbing in the mortgage system bloated the third, and the fourth chased all three upmarket, to the $500k house where the “math still worked.” The average new house sold in America now costs $508,800.
Ask what a for-sale homebuilder is and you will get an answer that was true in 1995: someone who buys land, spends years entitling it, borrows against it, builds houses on it at her own risk, and sells them for a margin that pays him back for the years and the risk.
Every clause in that sentence is now optional.
Between last spring and last week, three systems that never coordinate all moved in the same direction. State legislatures began repealing the local rules that define the lot. Congress struck the requirement that deformed the factory-built house for fifty years. And the agency mortgage rail now funds land and factory built construction on the consumer’s balance sheet instead of the developer’s.
Together these redefine the industry.
Margin x Velocity
Every development business obeys one identity, whether or not its operator ever writes it down: ROE = margin x velocity. What you make per dollar of house, times how many times a year each dollar of equity gets to do it.
For fifty years the industry optimized the first term because the second was bolted to the floor. Entitlement was a multi-year discretionary gauntlet. Stick framing meant 12 months of vertical work, all of it outdoors. And the financing structure put the whole build on the developer: $250,000 or more of work-in-process per started home, carried until a buyer closed.
So the industry pulled the only lever it had, margin, and became what it actually is beneath: a warehouse for risk. Land risk, entitlement risk, construction risk, rate risk, absorption risk, stacked on one balance sheet and compensated by gross margin. The house is the byproduct of warehoused risk. Readers who carry the DuPont identity around in their heads will notice the third term lurking here too. The classic way to make warehouse math produce a respectable return on equity was to lever the warehouse, which is why 2008 gutted the industry.
The best-performing homebuilder stock of the modern era belongs to the company that read the tea leaves first. NVR emerged from its early ‘90s restructuring having sworn off land ownership; it optioned finished lots instead, and moving land off the balance sheet produced returns on capital the rest of the industry has spent thirty years failing to match. Everyone learned the lesson. Then Lennar went “land-light” and the lot-banking complex was born.
Vertical risk stayed exactly where it had always been, because moving it required something that did not exist: somebody else willing to fund the construction of an unbuilt home, at scale, at a cost of capital below the developer’s.
The Lot Became a Statute
Entitlement risk was the developer’s moat and her jail at once. It made the business slow, local, and relationship-driven, and it paid her for surviving it.
State legislatures are repealing it. Idaho, where home prices ran away from local wages about as badly as anywhere in America after 2019, passed a slate of housing bills this spring. SB 1352 bars cities over 10,000 people from requiring lots larger than 1,500 square feet in starter-home subdivisions of four acres or more, at densities up to twelve homes an acre. HB 800 makes a manufactured home a permitted use on any single-family lot, HOA covenants excepted. Around them: accessory dwellings by right, a city option for single-stair apartment buildings, permit clocks measured in days instead of seasons. Nor is this an Idaho quirk. Texas capped minimum lots at 3,000 square feet in new subdivisions in its largest cities, which had typically demanded 5,000 to 7,500. Indiana made single-family homes and duplexes permitted uses, no public hearing required. Montana ran its “miracle” session in 2023 and kept going. The wave is bipartisan, supply-side, and preemptive.
Consider what a statute like SB 1352 actually manufactures. The entire category was conjured by statute, statewide, in a single legislative session, and the discretionary process that used to stand between a developer and that lot was replaced by a conditions checklist. What used to take two years of hearings is now a column in a database.
The fight over the American lot is moving from the planning commission to the utility ledger, and the will-serve letter is becoming the new entitlement. The scarce input is now serviced ground with water and sewer at the lot line. Another database column.
The Manufactured Home Lost Its Chassis
The steel chassis under every manufactured home was the price of a 1974 political bargain. The HUD Code gave factory housing the only federally preempted building code in America: one factory could ship into fifty states without ever touching a local plan-review desk. In exchange, the home had to remain, legally and structurally, a vehicle, with a permanent chassis under every section, forever. Fewer than 5% of manufactured homes ever move again after initial placement, but every one of them carried the frame. The steel added as much as $10,000 a home and made a second story a structural fight. Worse than either, it kept the product legible as a trailer to appraisers, to lenders, to zoning boards, and to neighbors. The chassis kept factory housing appraising like a depreciating asset, financing like a car, and zoning like a use to be quarantined.
On July 11 the bargain ended. The 21st Century ROAD to Housing Act passed the Senate 85–5 and the House 358–32, then became law without a presidential signature. Section 301 strikes the permanent-chassis requirement from the federal definition of a manufactured home.
A law change does not ship product. HUD’s construction code has to catch up through rulemaking, and rulemaking runs on HUD’s clock. But the clock is already running. HUD proposed a rule in June that frees upper stories from the chassis, with comments closing August 11. A chassis-free home cannot be ordered today, but it now arrives on a schedule you can underwrite.
And the bridge is already built. A CrossMod, a HUD-code home on a permanent foundation, with a pitched roof, a site-built porch, a site-built garage, qualifies under Fannie Mae’s MH Advantage and Freddie Mac’s CHOICEHome, which the GSEs have aligned into a single spec. And where MH Advantage comps do not yet exist, Fannie’s own guide directs the appraiser to supplement with site-built homes, at least two of them, “in recognition of the design standards” of the product. Hold that thought. It is the hinge of this whole story.
The cost side is not subtle. In the most careful side-by-side we have, Harvard’s Joint Center priced a CrossMod at $147,000 against $201,000 for its site-built twin: 27% less. A basic single-section home was 65% cheaper than site-built. The product could be cheap, or it could be legible as real property, and the chassis guaranteed it could never quite be both. Striking the chassis attacks the trap itself.
The reasons factories are cheaper are boring and permanent. Year-round production in climate control, an assembly line’s labor productivity, bulk purchasing, a fraction of the waste. Two-story, small-footprint factory homes are precisely what a 1,500-square-foot lot wants and precisely what the chassis forbade. Statute changes manufacture a lot that no existing product fits. The elimination of the steel chassis manufactures the product.
The Construction Loan Changed Hands
Fannie Mae’s single-closing construction-to-permanent program now extends to manufactured homes. One loan, closed once, funds the land purchase, the factory order, and the site work. The lender disburses draws to the contractor as work completes, the construction period is capped at twelve months, and at completion the note converts automatically into the permanent mortgage for the buyers at a 30 year fixed rate. The buyer signs once.
Now read that from the developer’s chair. The buyer’s agency-backed mortgage, the cheapest and most standardized credit in America, is funding the riskiest phase of the deal. The consumer’s mortgage became the construction loan.
In this configuration the developer is not a builder of inventory. She is the contractor of record on the buyer’s loan. She signs at the sale price, subcontracts the factory to build and set the home, subcontracts the trades for foundation, finish, and hookups, and collects draws from the buyer’s lender as the work completes. The vertical cost, the line that has defined homebuilding balance sheets since Levittown, never touches her. It flows from the agency rail, through her, to the factory and the trades.
A traditional spec builder carries absorption risk. This model cannot carry that risk, because it cannot spec: every vertical is sold before it is financed. What it carries instead is pipeline risk. The buyer who cancels in month two. The rate lock that dies in month four. The as-completed appraisal that comes in light. Those risks are real, and managing them is why the lending desk and the draw administration belong inside the machine rather than outsourced to whichever loan officer answers the phone. The rail exists; lenders who run manufactured-housing construction draws competently are still scarce. Scarcity in the plumbing is the opportunity, for whoever owns the plumbing.
This is the second half of the thought NVR started in the ‘90s. Lot options moved the land off the developer’s balance sheet. Consumer construction-to-perm moves the construction off. What remains at risk is dirt, pipes, paper, and interest. Everything else belongs to somebody with a lower cost of capital than the builder will ever have.
Velocity Is the Product
I have been underwriting this configuration on the ground in Idaho’s Treasure Valley.
At-risk capital runs about $50,000 per lot: land basis plus the horizontal: streets, mains, and laterals. A conventional spec builder on comparable ground carries $250,000 or more per started home.
There are two clocks here. The structure’s delivery timeline runs about 120 days: 60-90 for the factory to build, 30-45 for the site crew to set, finish, and reach certificate of occupancy, against 10 months for the stick builder. The developer’s money is not at risk; the buyer’s lender’s is. The developer’s dollar goes into the ground when the pipes go in and comes back lot by lot as homes close, so its speed is set by absorption. On a small project at an unheroic sales pace, a dollar of horizontal equity is out about eight months, call it 1.5x turns, against the spec builder’s 0.86x at a fourteen month cycle.
Margin per home runs perhaps 30-40% of what the spec builder books, and it does not matter. A quarter of the margin, on a fifth of the capital, turning on the 120-day home clock comes out to six times the spec builder’s return on equity. That is naive. Put the equity on its honest clock and six becomes three. Charge the model home, the contingency, and the disappointments, and three becomes two. Two is the number I will defend: twice the spec builder’s return on equity, with no vertical costs on the balance sheet and nothing built that is not sold.
The spec builder matching this pricing means doubling her gross margin, to something around 40% on an entry-level product, from buyers already at the debt-to-income ceiling of what they can bear.
Notice what the developer has become: a dealer that recycles infrastructure equity, with a contracting margin attached. The job is to underwrite serviced dirt, install the horizontal, and run consumer-funded verticals across it as fast as the factory can ship. Velocity is the model. And velocity, unlike margin, compounds.
The Job Migrates to the Screen
If the statute defines the lot, the factory defines the house, and the agency rail defines the money, what does the developer still do that is scarce?
She finds coordinates.
The binding constraint has moved to the top of the funnel: querying the parcels where all three rails intersect. Four or more contiguous acres, inside city limits, with a municipal population above the statutory threshold. Utilities service is what makes preemption binding, so service is the screen’s most important column. Ask price under a ceiling per buildable lot. Sane slope, out of the floodplain. Every condition is a field in a database, and none of them requires knowing anyone at the country club.
This is where the software layer stops being a curiosity. Acres, the land-intelligence platform, covers more than 150 million parcels with 45 million land transactions behind them, including sales in non-disclosure states; Lennar and Century Communities are already customers. When the deal is defined by statutory thresholds instead of local discretion, land acquisition becomes systematic origination: run the screen daily across every preemption state, rank by basis and service, feed the machine. The land banker’s golf network was a pricing mechanism for information that was scarce, local, and social. The statutes made that information legible and software makes it liquid.
We have watched this movie in another asset class. When underwriting standardized, mortgage origination stopped being a craft and became a funnel, and the winners were whoever built the best machine at the top of it. The same migration is starting in land, and it will end the same way: once the machine is commonplace, standardization compresses everyone’s returns.
One more scarce thing, while we are counting. Factory slots. The entire HUD-code industry ships roughly a hundred thousand homes a year, against site-built starts an order of magnitude larger. If even a modest share of starter-home demand routes to the factories, capacity will be allocated long before it is built, and slots will behave the way finished lots behaved in 2021: claimed early, by whoever showed up with a forward commitment.
The developer of 2030 will look less like a builder and more like an originator. A parcel screen running across a dozen preemption states. Allocated factory capacity. A lending desk that controls the buyer’s closing. A small equity base recycling through dirt and pipes.
The Window
Timing matters more here than it usually does, because appraisal is precedent.
Recall the hinge. On the agency rail, the loan is sized against the as-completed appraisal, and where MH Advantage comparables are missing, Fannie’s guide sends the appraiser to site-built sales. No Idaho appraiser has comped a two-story CrossMod duplex on a 1,500-square-foot lot, because until this spring the lot was illegal and the house was impossible. The first closed transactions become the comparables every later transaction inherits. The first developer through writes the reference prices for the category.
Once the comps exist and the configuration is public knowledge, returns compress toward commodity, and the advantage reverts to whoever built the origination machine. Before that, someone has to be first. The prize for being first is not permanent margin. It is the machine, the slots, and the comps, acquired while they were cheap.
The Street
None of this is an IRR story.
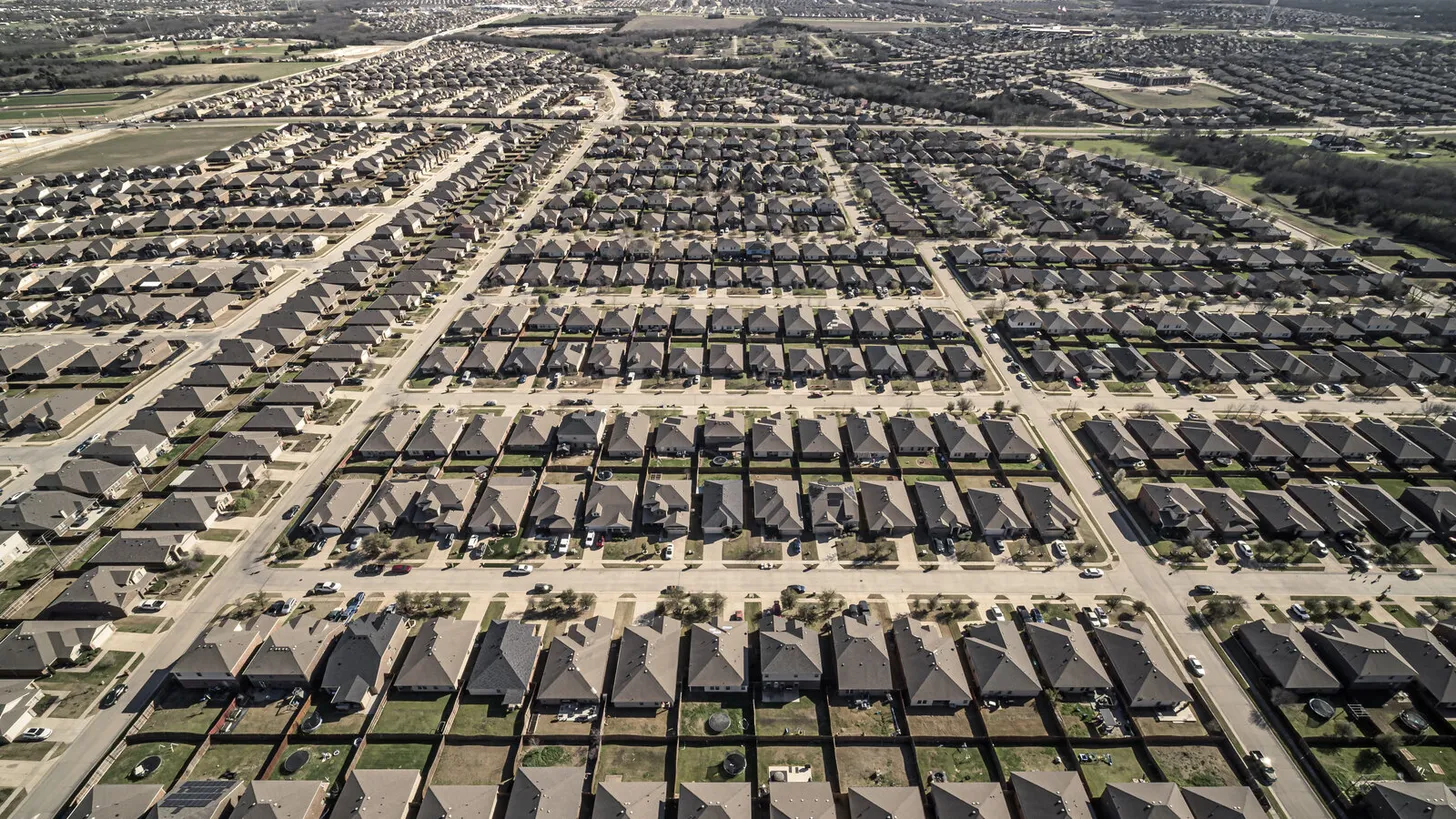
Take four acres inside an Idaho city. Their new small lot statute allows up to 12 homes an acre. A real plan, after streets, alleys, stormwater, and a commons, yields about 33. Picture them: 33 porches facing each other across a narrow right-of-way, cars pushed to the alley behind, two-story homes at prewar streetcar-suburb scale. The people on those porches earn $70,000 to $90,000 a year. The same demographic staring at resale inventory quietly accepted that owning was not going to happen. Now they hold new construction at a fixed rate, for a payment within a few hundred dollars of the rent they were already paying.
The 20th century built that street fabric casually and then spent 70 years making it illegal. For the first time in a century, the legal lot, the physical house, and the financing rail that can deliver that street profitably all exist at the same moment.
So what is a for-sale developer now? An origination business. The statute makes the lot. The factory makes the house. The buyer’s mortgage makes the money. Software finds the ground. Equity has exactly one job left, and it is not to sit under framing lumber for two years. It is to put in the pipes, set the precedent, and move.
The developers who understand they are in the velocity business will build the next decade of entry-level America. The ones still warehousing margin will keep wondering why their return on equity never matches their gross-margin story.
There is a specific parcel behind this essay; the model is downstream of the insight. If you want to see it: peter@serieshomes.com.